Updated September 14, 2026
Tokenization is the process of representing an asset or a right using digital tokens, often on a blockchain. Those tokens might represent company shares, units in a fund, a loan or rights connected with property.
This guide focuses on asset tokenization and what it means for investors. The same word appears in payment security and artificial intelligence, where it describes different processes.
TL;DR
Tokenization provides a digital way to record and transfer rights connected with an asset. It can support smaller investment units and automated processes, while returns and resale still depend on the investment itself.
What Is a Token?
A token is a digital unit recorded within a computer system, such as a blockchain. In asset tokenization, it represents a defined interest, claim or right.
For example, a token might represent one share in a company that owns a rental property. Another could represent a unit in a fund holding government bonds.
The documents behind the investment explain what the holder is entitled to receive. These might include income distributions, voting rights, repayment or a share of future sale proceeds.
A Simple Tokenization Example
Imagine a company owns a rental property worth $500,000, with no mortgage. For this simplified example, its entire equity is represented by 50,000 equal tokens priced at $10 each.
You buy 100 tokens for $1,000. That gives you 0.2% of the company’s equity, assuming every token carries the same rights.
If the company distributes $20,000 among those holders, your share would be $40 before any personal taxes. This illustrates the calculation and does not predict an actual investment return.
The company owns the building, while you hold an interest in the company. Your entitlement to income or sale proceeds follows the investment documents.
Real offerings may also include debt, purchase costs, management fees and cash reserves. These affect the investment’s value and the money available for distribution.
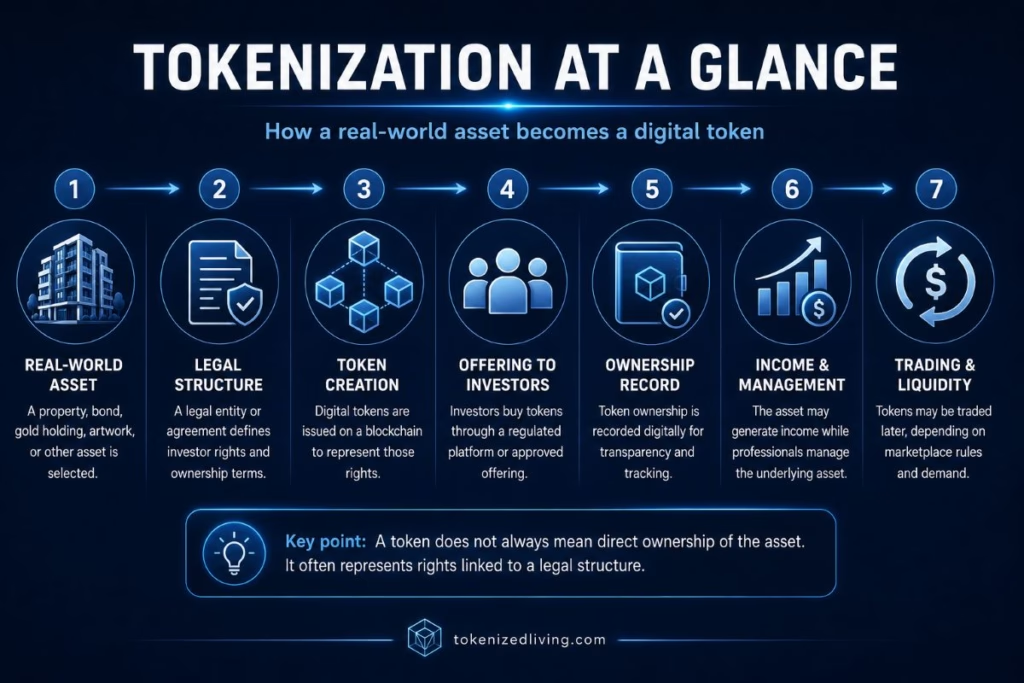
How Does Tokenization Work?
The process starts by identifying the asset and defining the rights investors will receive. Depending on the product, this may involve a company, trust, fund or debt agreement.
Next, the issuer creates tokens and connects them with those rights through the required documents and records. The technical setup determines how tokens are issued, held and transferred.
Eligible investors can then buy tokens through the offering’s approved process. Identity checks, country restrictions and payment methods depend on the product and its legal framework.
After issuance, the asset still needs ongoing management and reporting. Rental properties need maintenance, borrowers need to repay loans, and funds need administrators.
Transfers, distributions and eventual exits follow the product’s rules. Some arrangements offer resale, while others expect investors to remain invested until a sale or repayment date.
What Do Token Holders Actually Own?
The word “token” describes the digital unit, but does not tell you its legal meaning. Two products using similar technology can give investors very different rights.
| Token structure | What the investor may hold |
|---|---|
| Company equity | Shares or membership interests in an asset-owning company |
| Fund or trust interest | Units or beneficial interests governed by the fund or trust documents |
| Debt | A claim for payment under a loan, bond or other debt arrangement |
| Asset ownership claim | Rights to an underlying asset under specified custody or registration arrangements |
A shareholder and a lender have different claims, even when both investments finance the same property. Their payment terms, decision-making rights and treatment during financial difficulties may differ.
The SEC’s January 2026 staff statement describes several tokenized securities models with different ownership and record-keeping arrangements. It also explains that using a tokenized format does not remove the application of US securities laws, as outlined in its statement on tokenized securities.
Why Use Blockchain?
A blockchain can maintain a shared record of token balances and transfers. This can help participants work from consistent records instead of repeatedly reconciling separate databases.
However, a wallet address does not necessarily reveal the legal identity of its holder. Identity information and the official ownership register may sit partly outside the blockchain.
Smart contracts are programs that carry out specified actions when their conditions are met. For example, they can restrict transfers to approved wallets or distribute available funds according to programmed rules.
The Bank for International Settlements describes how tokenization can combine asset records with rules governing their transfer. Its explanation of tokenization and programmable platforms provides the broader financial context.
What Are the Potential Benefits?
Smaller investment units
Tokenization can let an issuer divide an investment into smaller units. This may allow investors to participate without funding an entire property or another expensive asset.
Traditional funds and REITs also offer fractional exposure. The entry amount therefore depends on the product, rather than blockchain alone.
More efficient administration
Digital records and automated instructions can reduce some manual work. Potential uses include updating balances, processing approved transfers and calculating distributions.
The actual saving depends on how the whole system operates. Banking arrangements, identity checks and legal procedures can still take time.
Rules built into transfers
A token system can apply conditions before allowing a transaction. For example, it may permit transfers only between investors who have completed the required checks.
This can help administrators apply certain rules consistently. The software still needs accurate information, appropriate controls and maintenance.
What Are the Main Limits and Risks?
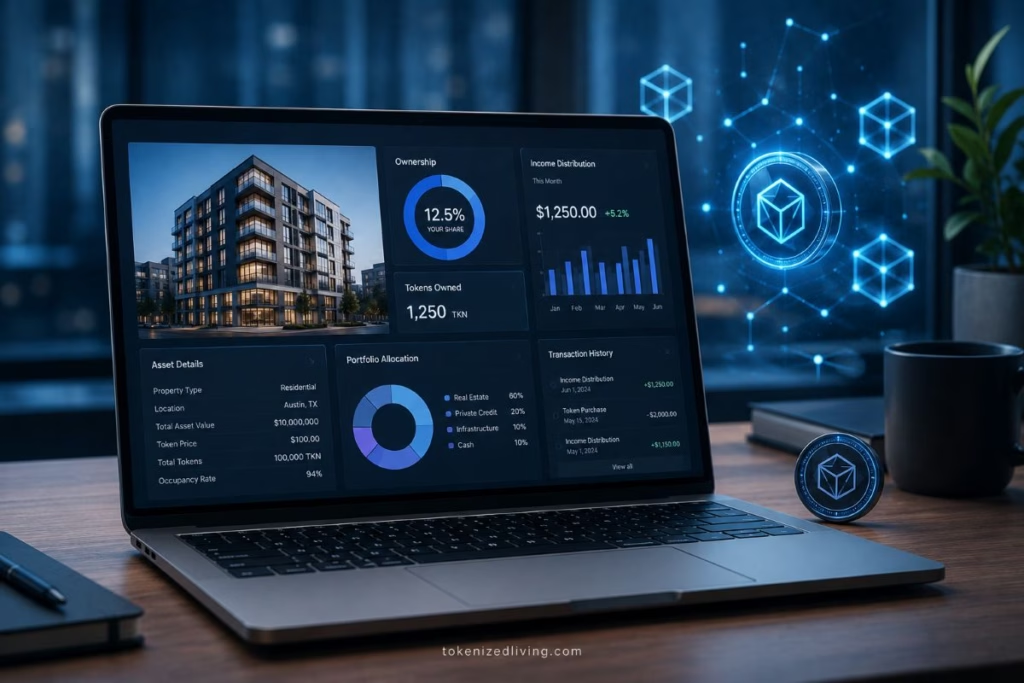
Tokenization changes how an investment is recorded and handled. The asset’s income, expenses, debt and market value still shape its financial performance.
For property, vacant units or major repairs can reduce distributions. With debt products, missed repayments can affect both income and the recovery of invested money.
There are also technical and service-provider risks to consider. Software errors, stolen credentials, custody failures or platform outages can interfere with access and transfers.
A visible blockchain transaction history provides information about activity within that system. Property condition, unpaid bills and other outside events require separate reporting.
Fees deserve attention because several charges can apply to one investment. Review the total cost of buying, holding and selling, including management and currency-conversion charges where relevant.
Can You Sell Tokenized Assets Easily?
Resale depends on finding an eligible buyer and completing the required transfer process. A token can move quickly between wallets once a sale is agreed, while finding that buyer may take much longer.
A marketplace listing shows that an investment is offered for sale. Actual transaction volumes, recent prices and waiting times provide better evidence of how readily investors can exit.
Some products restrict transfers or allow withdrawals only during set periods. Others rely on a property sale, loan repayment or another event before investors receive their capital back.
For example, imagine listing a token for $10 when the only available buyer offers $8. You must decide whether to accept the lower price or continue waiting, subject to the product’s rules.
Tokenization and Fractional Ownership: What Is the Difference?
Fractional ownership describes how an asset or investment interest is divided among holders. Tokenization describes how rights are represented using digital tokens.
Several investors can own shares in a property company through a conventional company register. Equally, a token can represent an entire asset or a debt claim without creating fractional ownership of that asset.
The two approaches can work together, as in the rental-property example above. However, smaller investment units alone do not require blockchain technology.
What Types of Assets Can Be Tokenized?
Real estate investments can involve rental homes, commercial buildings, development projects or property loans. The token may represent equity, debt or another interest connected with those assets.
Financial products can include company shares, bonds and fund units. Each retains the underlying product’s economic features, alongside any additional terms introduced by the token arrangement.
Physical assets such as gold, art and collectibles can also support tokenized products. These require clear arrangements for custody, valuation and any right to redeem or sell the underlying item.
Music-related products may provide rights to specified royalty payments. The documents should identify the income covered and how it reaches investors.
What Should Beginners Check?
Start with the legal documents and identify precisely what the token represents. Confirm who owns or holds the underlying asset and who maintains investor records.
Next, establish how any income or repayment reaches you. Check the payment source, expenses, reserves and circumstances that could delay or reduce payments.
Review the exit arrangements before committing money. Look for transfer restrictions, redemption terms and evidence of completed resales where a marketplace exists.
Finally, check what happens if the platform stops operating. The documents should explain who maintains records, manages the asset and handles investor claims.
Our tokenized real estate platform comparison applies these questions to different property investment models. Use it once you are comfortable identifying the rights behind a token.
Where to Go Next
For a wider look at asset types and investment structures, read our beginner’s guide to RWA tokenization. It expands on how real-world assets connect with digital investment systems.
If property is your main interest, continue with our complete guide to tokenized real estate. That guide covers property structures, income, costs and the practical questions involved in choosing an investment.
Frequently Asked Questions
What is tokenization in simple terms?
Tokenization means representing an asset or a right using digital tokens. In investing, those tokens can represent shares, fund units, debt claims or other interests.
Is tokenization the same as cryptocurrency?
Asset tokenization and cryptocurrencies can use the same blockchain technology. Their purpose and the rights they provide may differ, so the token’s label alone tells you little about the investment.
Do I need a crypto wallet?
Some platforms require investors to use their own compatible wallet. Others provide custody or an account interface that handles the underlying token arrangements.
Does a property token give me part of the deed?
That depends on the legal structure and registration arrangements. Many products instead give investors shares in a property-owning company or another claim connected with the property.
Does every tokenized asset pay income?
Income depends on the underlying asset and the product’s terms. Some investments distribute rent or interest, while others rely mainly on a future sale or redemption.
Can I lose my investment?
Losses can result from asset performance, borrower default, legal problems or failures involving the platform or technology. Depending on the product and circumstances, you could lose some or all of the amount invested.